Flip vs. BRRR in Greater Cincinnati: A Neighborhood-by-Neighborhood Strategy Guide
Flip vs. BRRR: Which Cincinnati Neighborhoods Favor Which Strategy
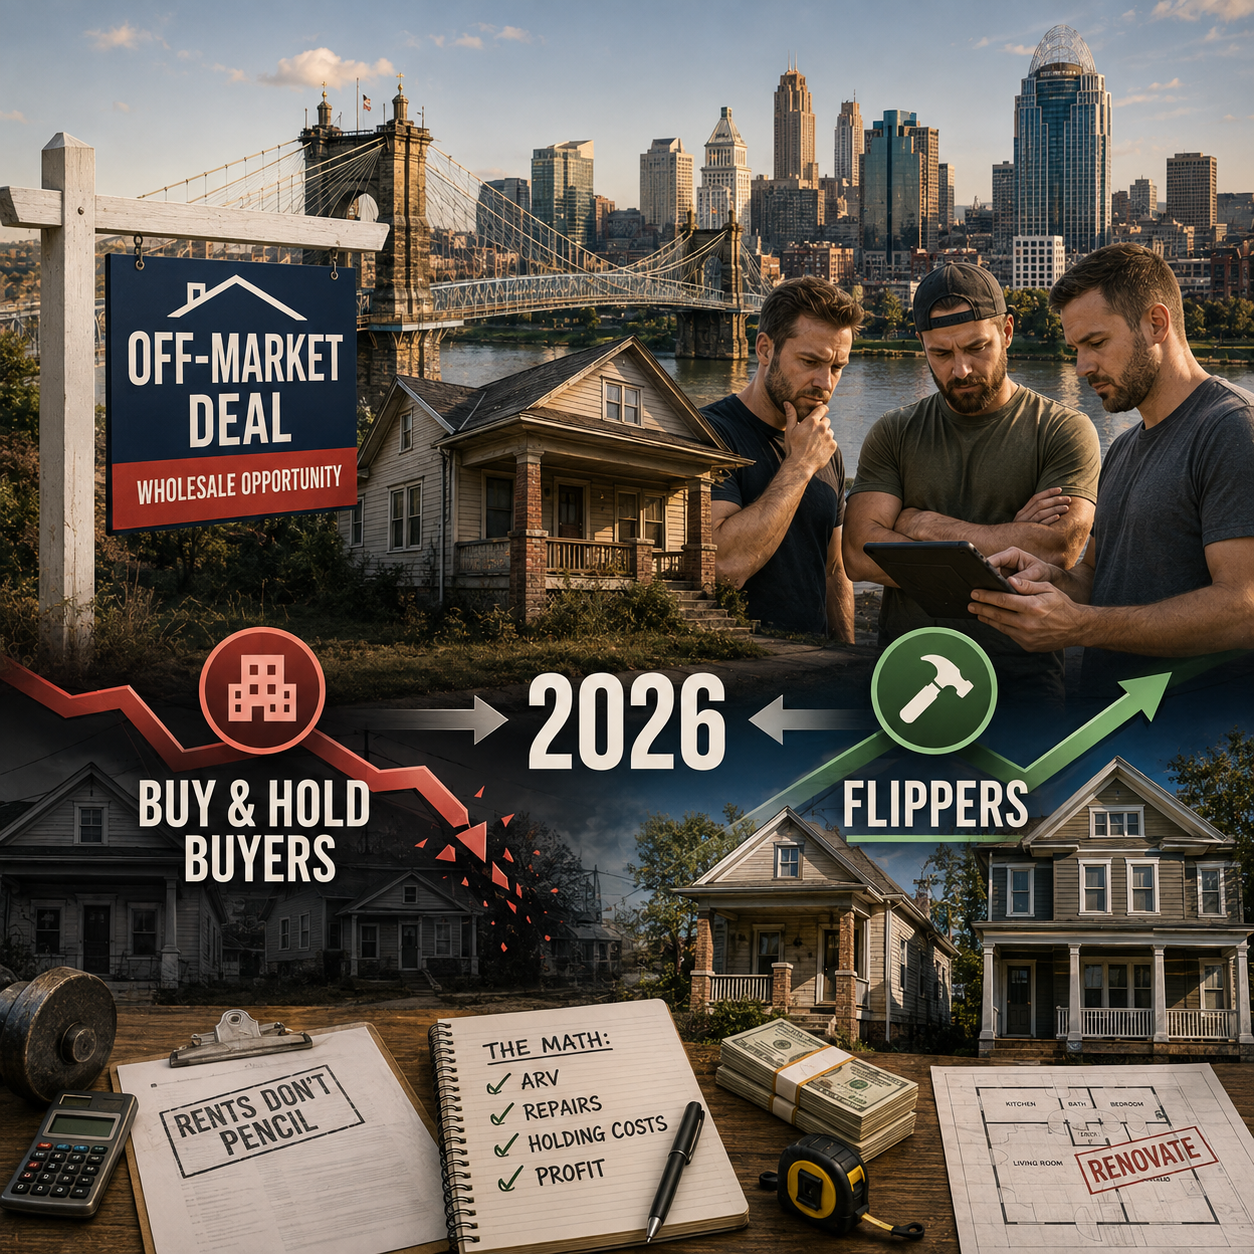
Cincinnati's flip vs. BRRR split is not random. It follows a pattern tied to one core question: do the rents support the hold?
When ARVs rise faster than rents, the math points toward selling. When rents produce a strong yield relative to all-in cost, holding wins. That ratio varies street by street across Greater Cincinnati. Here is where each strategy is producing results right now.
Neighborhoods trending toward BRRR:
- Middletown: Roughly 80% of investor exits here are refinances, not sales. Investors are buying, rehabbing, pulling cash out, and holding. The rent-to-price relationship in Middletown makes the hold strategy the obvious move for most operators entering the market.
- Price Hill corridor (west side): Primarily rental activity. Investors running Section 8 and long-term hold strategies dominate this pocket. Few flips pencil here.
- East Price Hill: Operators with deep market knowledge are building large Section 8 portfolios here. Not the easiest market to break into, but producing strong results for those who know the streets.
Neighborhoods trending toward flips:
- Kennedy Heights: The most active flip pocket in Greater Cincinnati right now. Six months ago, that was not the case. Kennedy Heights hit its inflection point when a fully renovated home set a new ARV ceiling. Other investors followed that comp. Activity has been concentrated here ever since.
- The I-75/I-71 corridor (Avondale north through Deer Park): Almost entirely fix-and-flip from a lending perspective. ARVs land in the median household price range, but rents top out around $2,000 to $2,500 for a single-family or duplex. That ceiling makes the hold case hard to justify.
- Cheviot and Westwood: Meaningful flip activity. Active market. Shifts back toward rentals as you move further south toward Price Hill.
- Delhi: Flip activity resurfaces here after the Price Hill rental corridor.
Neighborhoods running both strategies:
- City of Hamilton: Running roughly 50/50. Half of investor exits are refinances, half are on-market sales. Hamilton is one of the most nuanced markets in the MSA and is worth its own breakdown below.
- Norwood and Pleasant Ridge: Still active on both sides, but showing signs of maturity. Kennedy Heights is next in line precisely because investors are getting priced out of these two pockets.
3 early signals a neighborhood is shifting from BRRR to flip territory:
- A fully renovated comp sets a new ARV ceiling that did not exist 12 months ago.
- Surrounding neighborhoods have appreciated and are pricing investors out, pushing activity north or east.
- Rent growth is lagging behind price appreciation, compressing yield on holds.
Kennedy Heights showed all three. Watch Silverton next.
Why Cincinnati's Sub-$300K Market Keeps Producing Deals
The arithmetic behind Cincinnati real estate is straightforward and it does not get discussed enough.
You cannot build a house for $200,000. In Cincinnati, this matters more than almost anywhere because such a large share of the housing stock sits at or below that threshold. That creates a durable opportunity for investors who understand it.
The supply and demand picture:
The number of single-family homes in Greater Cincinnati worth less than $250,000 is fixed. In fact, it is shrinking. As investors renovate and reposition properties, some of those homes cross above the affordability threshold permanently and never come back.
Cincinnati has posted roughly 2% year-over-year population growth. Not a headline number, but it is steady directional demand against a supply that only moves one way.
At least 50% of active rehab deals in Greater Cincinnati right now carry an ARV under $300,000. This is not a niche corner of the market. It is the core.
Why this keeps producing returns:
Renovating distressed homes remains the fastest path to returning good inventory to the market. Most of Cincinnati's housing stock is 80 to 100 years old. New construction at affordable price points is slow, expensive, and nowhere near demand. Rehab fills the gap and has continued producing deals through rate cycles and market shifts going back at least to 2010.
The long-term hold thesis in three points:
- Limited supply in the sub-$250K single-family segment is structural, not cyclical.
- Steady population growth creates consistent rental demand across Middletown, Hamilton, and the west side corridors where new construction is essentially nonexistent.
- Every property that gets renovated past the affordability threshold reduces the available inventory, making the remaining stock more valuable over time.
- Investors who are buying and holding in this segment are not making a speculative bet. They are making a supply-and-demand bet with fixed inputs on one side.
What's Working in Cincinnati
The investors producing the most consistent results in Greater Cincinnati right now are not winning on market timing. They are winning on edge. Four specific competitive advantages keep appearing across hundreds of deals.
The 4 edges separating winning Cincinnati investors from the rest:
- Deal-sourcing advantage. The ability to find properties before they hit the market or before other buyers recognize the value. Off-market relationships, direct mail, wholesale networks. In a market this local and relationship-driven, knowing the right people compounds faster than any other single advantage.
- Construction cost advantage. This does not mean doing the work yourself. It means managing subs directly, knowing what things actually cost, and not paying retail on labor. Investors who have spent years building sub relationships in Cincinnati operate at a cost structure that newcomers cannot immediately match.
- Capital cost advantage. Hard money has a cost. Conventional financing has a cost. Private money and cash cost less. In the sub-$200K range, cheaper capital is often the difference between a deal that works and one that does not. The same is true at $500K+ for opposite reasons.
- Operational advantage. For investors holding rentals, this is what you do with the asset after you own it: occupancy management, rent growth, Section 8 optimization. Knowing voucher rates by zip code is a small thing. It makes operators move faster and underwrite more accurately on every deal.
3 markets where the playbook is well-defined for intermediate investors:
- Hamilton (Butler County): Strong deal flow, active investor community, both flip and BRRR strategies producing results. The Spooky Nook Sports Complex has been reshaping the west side of downtown for several years. Get specific on which streets before committing to a strategy.
- Kennedy Heights: Active flip market right now. New ARV comps are being set. Concentration of activity is high. Move with a clear business plan or wait for the next neighborhood to unlock.
- Middletown: Primarily BRRR. Consistent rental demand. Lower price points and a forgiving entry for investors building their first buy-and-hold portfolio in the Cincinnati MSA.
What does not work: Buying in a market you do not know well, running a playbook designed for a different neighborhood, or underwriting only what you can see in a city where most homes are 80 to 100 years old.
Lessons From the Field: What Older Cincinnati Homes Actually Cost You
The most consistent mistake investors make in Greater Cincinnati is underwriting only what they can see.
Most of Cincinnati's housing stock was built before 1950. When you open those walls, you find what three or four previous renovations left behind. Outdated systems brought up to code on each pass but never fully resolved. Plumbing that held until someone touched it. Structural elements that have been load-bearing for a century and finally cannot anymore.
A real example from Hamilton:
An investor acquired a property spread across three parcels: two homes and a garage. The plan was to hold it as a rental. Rehab started. City inspectors arrived.
Because the investor was touching the plumbing, Hamilton's building code required the shared sewer lines across the parcels to be separated. That work was not in the budget and not in the business plan.
The solution was to recombine all three parcels into one so the property could be treated as a legal duplex under a single parcel. Ohio Revised Code allowed it. The city approved it after some convincing. Then a cold snap hit while the plumbing work was paused. Pipes froze. When the water came back on, the freshly repaired lines burst. The same pipes were repaired twice.
Splitting the water lines at the start and moving on would have been cheaper. You do not always know that until you are already in it.
5 things Cincinnati investors consistently underestimate in older housing stock:
- Structural walls that have failed quietly behind plaster and drywall, with no visible exterior sign
- Shared utilities across parcels that trigger code separation requirements the moment you pull a permit
- Septic systems in Clermont County and other suburban areas (always inspect before waiving one)
- Pre-1950 electrical and plumbing that is technically functional but will need to be addressed once walls are open
- Local municipal code variations county to county that can change your business plan mid-rehab
The lesson is not to avoid older homes. It is to price them correctly. Build a contingency that assumes you will find something behind the walls. In Cincinnati, you will.
About This Post
This analysis draws from a conversation with Grant Smith, founding partner of Sharper Capital Partners and co-owner of Rowling Homes. Grant has funded 300+ deals across Greater Cincinnati and Northern Kentucky. His lending portfolio provides a real-time view of investor activity across every neighborhood in the MSA that almost no individual operator can match.
Listen to the full conversation on Spotify, Apple Podcasts, and YouTube. The episode includes Grant's live deal map walkthrough, his breakdown of the Spooky Nook effect on Hamilton, and a deeper discussion of how Rowling Homes operates as an off-market buyer.
The Cincy REI Show publishes every Monday. New episodes cover neighborhood-level analysis, local investor strategies, and real deal stories from operators active in Greater Cincinnati.