Why Cincinnati's Biggest Multifamily Deals Don't Pencil for Everyone

Lee Yoder holds 930 units, and almost none of them are near Cincinnati. Why institutional capital compresses returns above 100 units, and what he found in rural Ohio and Indiana instead.

Lee Yoder owns 930 units today, and only one property sits anywhere near Cincinnati proper. The rest run north through the northwest corner of Ohio and into the northeast corner of Indiana, in towns most Cincinnati investors have never heard of. Founder of Threefold REI, Yoder made that shift deliberately, not because he stopped liking Cincinnati real estate, but because the returns he needed stopped being available once his deal size crossed into institutional territory.

About This Post

This analysis draws from a conversation with Lee Yoder, founder of Threefold REI, who has taken three multifamily syndications full cycle and currently holds 930 units concentrated in northwest Ohio and northeast Indiana. Yoder's experience straddling both a small Cincinnati-area portfolio and a much larger rural multifamily operation gives him an unusually direct comparison point on where returns are actually available at different deal sizes.

Listen to the full conversation on Spotify, Apple Podcasts, and YouTube. The full episode also covers Yoder's decision to bring property management in-house after years working with a third-party Cincinnati management company, and more detail on his rent roll and leasing performance in Williamsburg.

The Cincy REI Show publishes every Monday. New episodes cover neighborhood-level analysis, local investor strategies, and real deal stories from operators active in Greater Cincinnati.

Why Yoder Left Cincinnati for Rural Ohio and Indiana

  • Williamsburg, Ohio, in Clermont County, is Yoder's property closest to Cincinnati, roughly 15 minutes from the outer belt on Route 32 past Batavia. The appeal is straightforward: cheaper land and rent than closer-in submarkets, a small school district, a walkable downtown with a coffee shop and donut shop, and easy access back to every Cincinnati amenity via the outer belt. Two-thirds of the unit mix is one-bedroom, one-third two-bedroom. One-bedrooms moved from $850 back up to $900 in early 2026 after a rough stretch; two-bedrooms have held steady around $1,100.
  • Northwest Ohio and northeast Indiana are where the bulk of Yoder's 930 units sit, in small towns like West Liberty, similar in character to Williamsburg but small enough that few investors outside a tight radius have heard of them. Yoder targets a minimum of 100 units per acquisition there specifically so the deal can support a dedicated on-the-ground team.
  • Cincinnati inside the outer belt, particularly for properties over 100 units, is where Yoder says he consistently loses to institutional buyers who have a lower cost of capital and target lower returns, since their investors are largely preserving existing wealth rather than building it. Yoder still finds smaller Cincinnati deals with a workable price per door but says he has lost interest in that segment now that his fund size requires bigger acquisitions.
  • The Cincinnati east side broadly, including the Eastgate area near Williamsburg, has seen heavy new apartment construction in the last several years. Yoder says that supply has occasionally pulled his own C-class tenants toward newer B-class product offerings with months of free rent as concessions, a pattern he expects to ease as those new deliveries slow into 2026 and 2027.

The Cap Rate Gap Between Cincinnati and Rural Multifamily

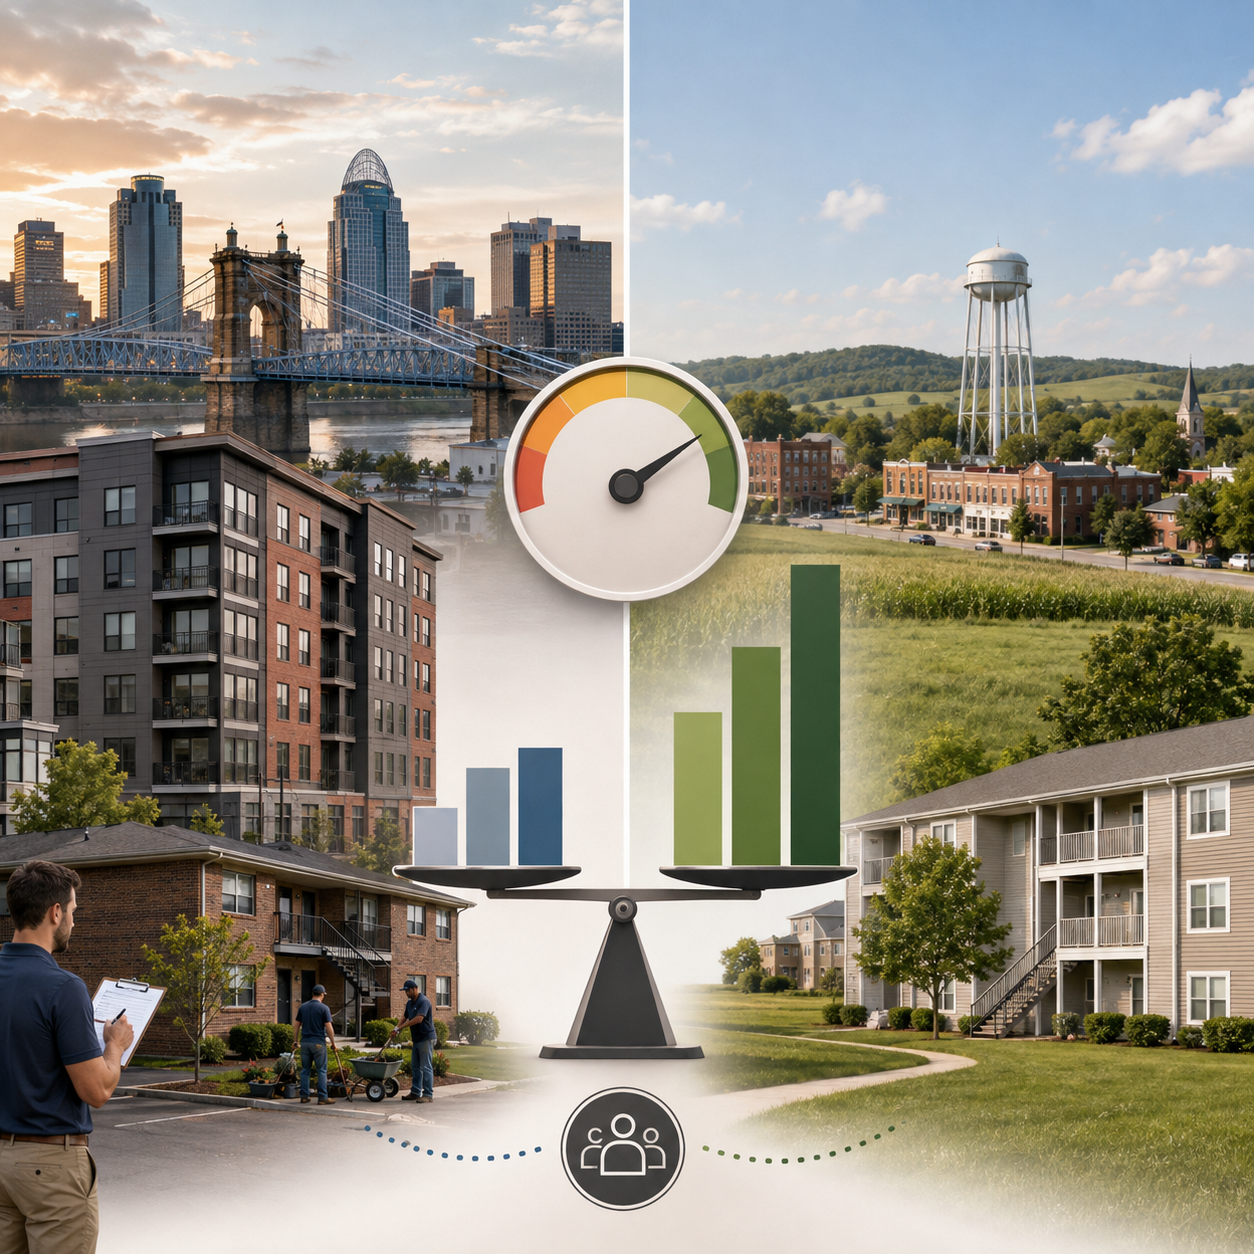
Yoder's underwriting numbers illustrate exactly why deal size drives where investors end up buying. On his rural Ohio and Indiana acquisitions, Yoder targets a going-in cap rate north of 7%, ideally around 8% on actual trailing numbers, with year-one cash flow around 7% climbing to 8% by year two. On comparable Cincinnati deals, he sees cap rates closer to 6% to 7% with year-one cash flow closer to 5% to 6%. Larger Cincinnati-area deals, the ones institutional buyers compete for, can compress further still, sometimes to a 4% to 5% cash-on-cash return in year one.


The mechanism behind that gap, in Yoder's view, is straightforward: preferred equity providers generally require a minimum check size, often $5 million, which effectively locks smaller deals out of that capital source and reduces competition on them. Larger, more expensive deals attract institutional buyers willing to accept lower returns because their investors have already built their wealth and are focused on preserving it rather than growing it aggressively.


This same logic underlies why Ian and Slocomb's own smaller, scatter-site Cincinnati acquisitions can compete effectively in the sub-100-unit range: analytical and operational expertise built specifically around smaller, harder-to-run properties, on-site staff on payroll instead of third-party management fees, lets them win bids institutional buyers won't pursue, achieving similar cap rates and cash flow to Yoder's rural portfolio without leaving Greater Cincinnati.
What's Working in Cincinnati (and Just Outside It)

Yoder's strategy comes down to a small number of deliberate choices about where to compete and how to hold.

  1. Go where the big players aren't. Yoder specifically targets deal sizes and locations that fall below the threshold institutional capital requires, whether that means staying under 100 units in Cincinnati or going rural at scale further out.
  2. Buy for cash flow, not a five-year flip. Yoder's earlier syndications targeted a shorter hold and exited faster than projected. His current portfolio is built around a 10-year hold horizon, planning to refinance around year five and return investor capital while continuing to collect cash flow rather than counting on a large sale-driven upside.
  3. Bring property management in-house once you have the scale and expertise to do it. Yoder worked with a Cincinnati-based third-party management company for years, learned the business from them, and eventually built an internal team once he understood the operation well enough to run it with tighter focus and lower cost, since the internal team's only incentive is making the properties profitable, not generating a separate management fee.
  4. Match capital investment to what the tenant base can actually pay. For C-class properties right now, Yoder deliberately avoids upgrading finishes like countertops or cabinets that are functional but dated, since C-class renters currently want affordability over upgrades they cannot pay for. Yoder's approach is to accept a lower rent, like $850 instead of $950, rather than force a renovation cost onto a tenant base that will not absorb it.

What is not working: assuming Cincinnati's headline market-wide rent growth numbers apply evenly across asset classes and unit types. Much of the reported growth is concentrated in single-family rentals and Class-A apartments, while Class-C one-bedrooms specifically have lagged or declined.

Lessons From the Field: What a Rent Leasing Platform Change Revealed About the Market

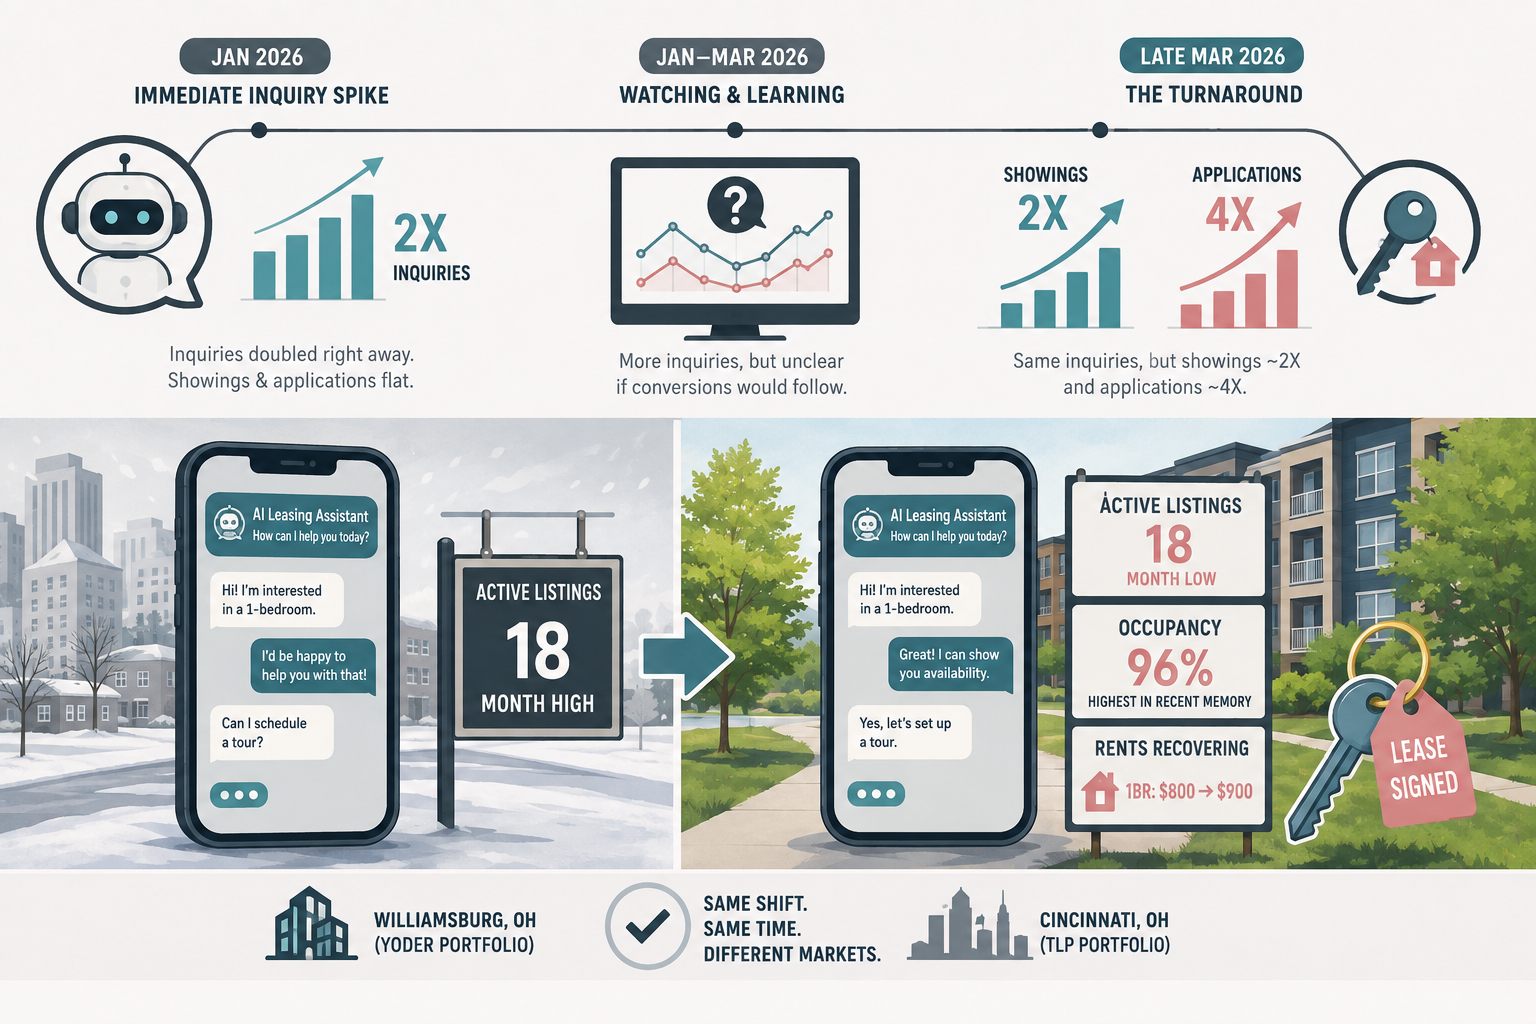
Both Yoder's Williamsburg property and Ian and Slocomb's own Cincinnati portfolio adopted AI-driven leasing software around the same time, January 2026 for TLP, and both saw an identical pattern play out over the following months.


The initial change was simple: an AI leasing assistant answering every inbound inquiry immediately, trained to identify itself honestly as AI rather than impersonate a human, with the ability to escalate to a person as soon as one became available. TLP saw inbound inquiries double almost immediately after the switch in January, but showings and applications did not follow at first. The volume increase was real, but conversion further down the funnel stayed flat through the winter.


The complication was ambiguity about whether the tool was actually working, since more inquiries without more signed leases could just as easily reflect a platform quirk as a genuine demand signal. TLP kept watching the data rather than assuming either outcome.


The shift came in late March 2026. Inquiry volume held steady, but showings roughly doubled and applications quadrupled from that same inquiry pool. TLP's active listings across its 420-to-450-unit portfolio dropped to the lowest point in 18 months. Yoder reported the same experience independently across his own portfolio during the identical window, one-bedrooms that had been stuck as low as $800 climbing back toward $900, and occupancy in Williamsburg reaching 96%, the highest in recent memory.

  1. A leasing technology change can surface a market shift before broader data confirms it. TLP recognized the March shift within about three weeks specifically because they had already been tracking their own inquiry-to-lease funnel closely since 2023.
  2. More inquiries do not guarantee more leases, at least not immediately. The gap between the January inquiry spike and the March conversion spike shows real demand and converted demand can move on different timelines.
  3. AI leasing tools require real setup investment before they perform. Both operators described a genuine break-in period training the AI on quirks and edge cases before it delivered clean results.
  4. Independent portfolios seeing the same shift at the same time is a stronger signal than either alone. TLP's Cincinnati experience and Yoder's rural Ohio and Indiana experience lined up almost to the week, despite having no shared management or geography.
  5. Class-C recovery lags Class-A recovery, and the timing gap itself is data. Rents for older one-bedroom stock only began recovering roughly 18 months after the August 2024 downturn began, well after Class-A rents had already stabilized and climbed.
October 14, 2026
How to Research the Cincinnati Market in Two Hours a Week
October 5, 2026
$110,000 from a wholesaler, $21,000 of work, a $200,000 appraisal. Ben Austin on the West Side streets he won't cross, and why he buys every property with two exits so he can decide later whether to flip or hold.
October 1, 2026
Cincinnati ranked fifth nationally for home price growth in April 2026, but the number that matters is replacement cost: whole neighborhoods still sell for less than it costs to build. Ian Cruz and Slocomb Reed answer the questions out-of-state investors ask first.
September 30, 2026
Venture has gone full cycle 32 times without missing pro forma. This year it offered rent concessions for the first time in 13 years. Robbie Hendricks on new supply, an 18-month soft stretch, and why every underwrite now assumes 0% rent growth.
September 29, 2026
How to Find Cash-Flowing Furnished Rentals in the Cincinnati Market in 2026
September 29, 2026
Contingent offers are back for the first time in five years and showings have slowed. Rebecca Sequeira, who has made money on every flip since 2016, on what she still buys, what she puts in every house, and when she cuts the price.
September 25, 2026
Self-manage if you're trying to save money. Hire out if you're trying to save time. Bri Leichliter built a Cincinnati property management company, sold it, and still owns five units — here's the math behind that split.
September 23, 2026
Houses that sold for $30,000 in Madisonville now trade at $125,000 to $150,000 still needing full renovations. A property manager with 700-plus units on where the next wave is going, and why the 12-unit building is the target.
September 22, 2026
Suburban office trades near a 10 cap while retail and industrial compress to six and seven. Tanh Truong on why half-empty office in Blue Ash is the one Cincinnati asset class where basis is still negotiable.
September 18, 2026
$1,900 in Winton Woods, $1,643 in Oak Hills, same bedroom count. What a 100-plus unit portfolio across nine districts reveals about which Cincinnati houses should stay rentals and which should be sold.
September 18, 2026
The renovation ran 2.5x over budget and produced 3x the rent bump. John Casmon on the Boone County data behind an 81-unit Florence buy, and the census-tract tool he uses instead of radius reports.
September 15, 2026
Cincinnati built almost no new apartments for 24 years. Gil Richards on the abatement math, which buildings qualify for historic credits, and why downtown is formally classified as Difficult to Develop.
September 11, 2026
Section 8 in Cincinnati: Why CMHA and Butler Metro Produce Different Returns
September 10, 2026
A rate cap that cost $30,000 renewed at $1.3 million. Joe Fairless on the first two losing sales in Ashcroft Capital's history and why Greater Cincinnati never had the spread to lose.
September 9, 2026
A $180,000 all-in flip selling for just under $270,000, with no cash out of pocket. Slocomb Reed breaks down four Greater Cincinnati deals, and why none of them depended on the market going up.
September 5, 2026
West Newport houses sold for $10,000 in 2016 and now go for $80,000 needing full rehabs. Garth Kukla on why proximity to a walkable corridor predicts Northern Kentucky value better than which city a property sits in.
September 4, 2026
The Hamilton County timeline from a missed rent payment to a set-out; and why TLP's Izzy Ong treats every case that reaches a magistrate as a failure of the process, not a win.
September 3, 2026
A $450,000 Loveland listing sold for $570,000 cash. Ethan Bishop on which Greater Cincinnati submarkets are drawing multiple offers, which have quietly cooled, and the two-generation demand pattern driving both.
September 2, 2026
Off-street parking, galvanized plumbing, school district lines that don't follow township borders, and a tax bill that can quadruple at closing. The Cincinnati-specific due diligence most investors skip.
August 31, 2026
JD Schmerge brokers Greater Cincinnati multifamily and operates a 7-unit in South Covington. Why tenants aren't paying for upgraded finishes, why insurance and taxes now outweigh interest rates, and how much to renovate before selling.
August 28, 2026
Bret Halsey went from pro soccer to 70-plus units in under three years, 14 of them fourplexes. How Cincinnati's repeating 1960s floor plans make the city's most common multifamily building the easiest one to underwrite.
August 27, 2026
Nine of 24 units were paying rent. Slocomb Reed took over management three months before closing, cleared the building, and proved higher rents; all before owning a share of it.
August 27, 2026
Reading, Ohio: Cincinnati's Unlikely Development Hotspot
August 26, 2026
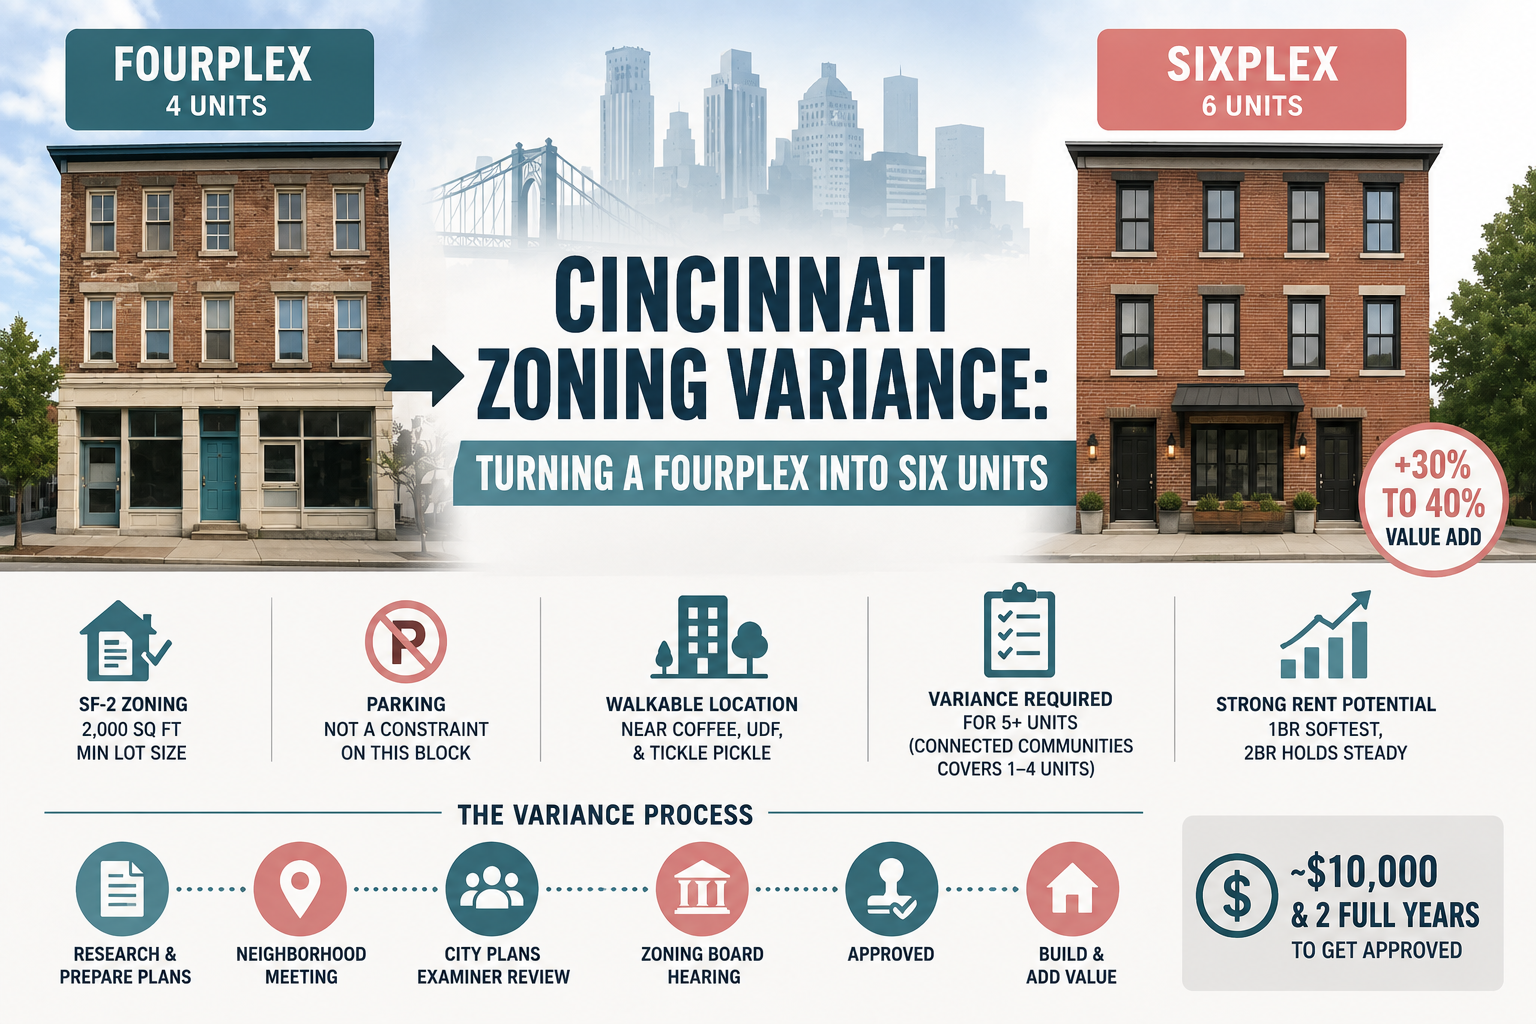
Two years, roughly $10,000 in zoning costs, and about 40 neighbor signatures. What Jeremy Komer's Northside conversion reveals about Cincinnati's variance process and the gap in Connected Communities.
By Ian Cruz • August 20, 2026
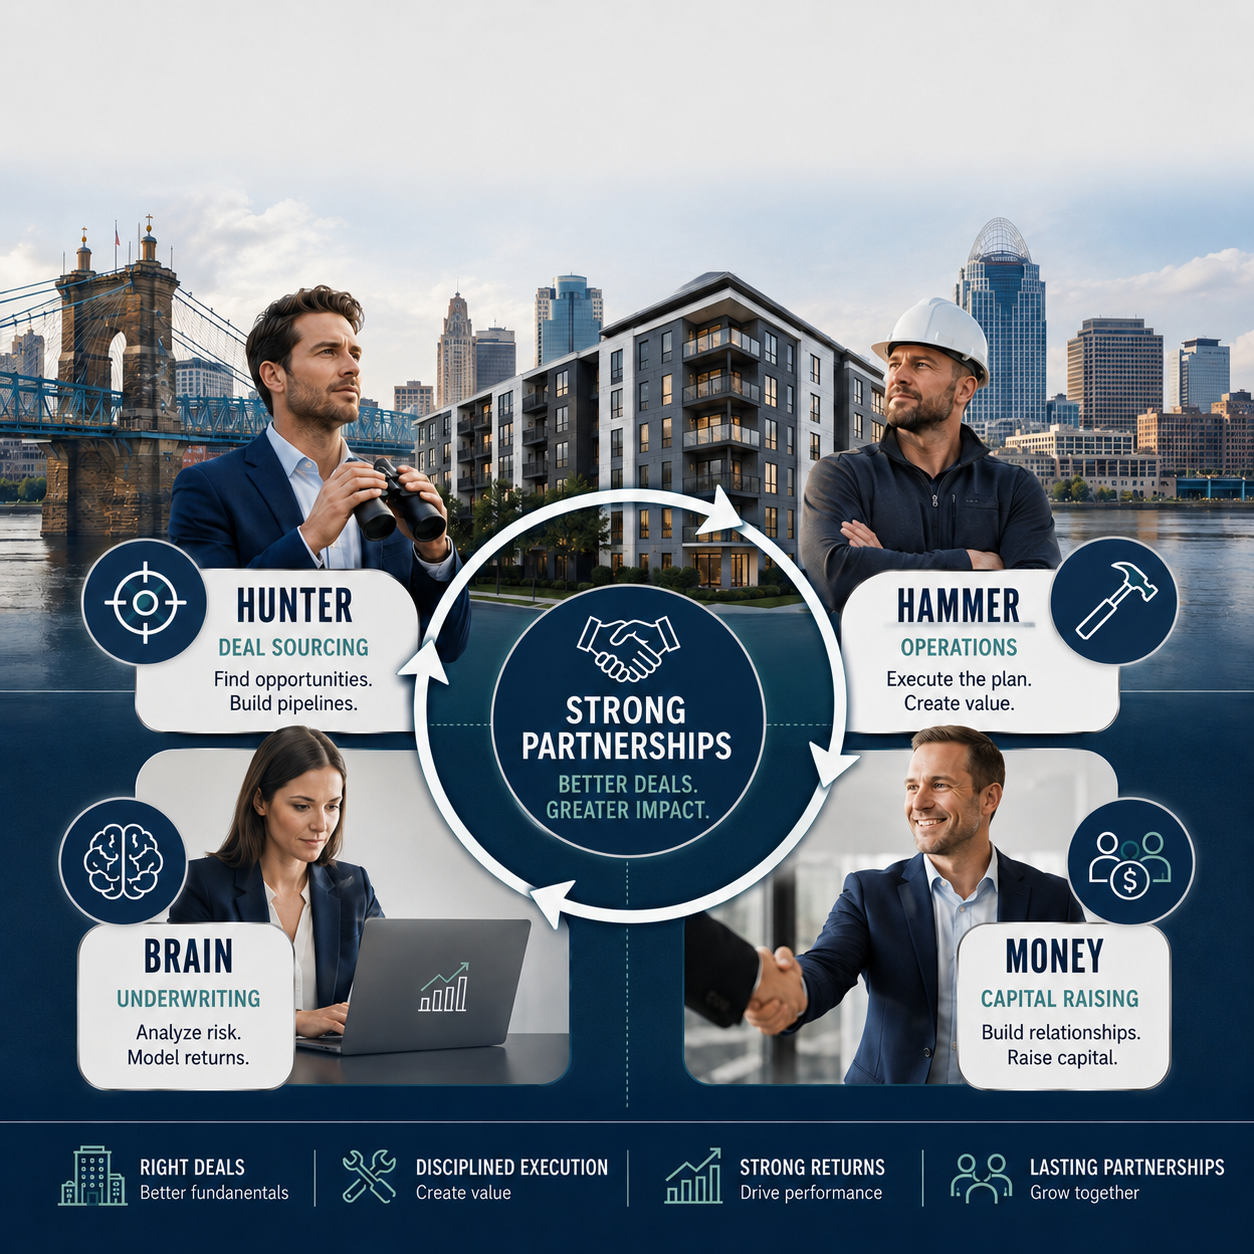
How Ian Cruz and Slocomb Reed used four defined roles to scale from an 8-unit Northside deal to 73 units in under two years — plus what Cincinnati's rental data shows right now.
August 20, 2026
Hedge funds are gone, rates broke the buy-and-hold math, and Cincinnati's off-market deal flow now turns block by block. Where the deals are and what buyers inherit when they sign.
August 20, 2026
A neighborhood-by-neighborhood map of where short-term rentals are legal in Greater Cincinnati; and what the flattening market means for the ones that are.
By Ian Cruz • August 20, 2026
Where Cincinnati Investors Are Still Finding Margin
August 18, 2026
What 300+ Transactions Reveal About Cincinnati’s Best Investment Strategies
June 12, 2026
Madisonville, Fairfax, and Newport: Where Cincinnati Investors Are Finding Margin in 2026
By Ian Cruz • June 5, 2026
Flip vs. BRRR: Which Cincinnati Neighborhoods Favor Which Strategy