Fairfax, Madisonville, and Newport: Cincinnati Real Estate in 2026

Where Cincinnati Investors Are Still Finding Margin

In Fairfax, empty lots that once sat overlooked are now selling for $120,000 to $150,000, driven almost entirely by proximity to the Mariemont school district. Jerry Garrison, a Keller Williams agent and single-family investor who has worked Greater Cincinnati real estate for two decades, has watched that price shift play out street by street, first in Fairfax, then in Madisonville, and now across the river in Newport, Kentucky.

About This Post

This analysis draws from a conversation with Jerry Garrison, a Keller Williams real estate agent and long-time Greater Cincinnati investor with two decades of experience across multifamily and single-family properties. His vantage point as both a working agent and an active landlord in Madisonville and Newport makes his neighborhood-level read unusually current.

Listen to the full conversation on Spotify, Apple Podcasts, and YouTube. The full episode also covers Garrison's take on Evanston, East Walnut Hills, and the Cincinnati west side, along with his advice for someone making their first real estate investment in 2026.

The Cincy REI Show publishes every Monday. New episodes cover neighborhood-level analysis, local investor strategies, and real deal stories from operators active in Greater Cincinnati.

Where Cincinnati Investors Are Finding Margin in 2026

  • Fairfax sits just west of Mariemont, close enough to the same school district to carry its price effect. Lots that trade around $120,000 are now targets for builders running a townhouse format: three bedroom, two and a half bath, with a finished lower level and a garage offset from the front entry where the lot allows it. The style fits parcels platted in 1884 or 1904, long and narrow, with living space stacked over three or four floors instead of spread across a yard.
  • Madisonville is where Garrison bought his first rental in 2017, a house on Britton Street for $105,000. He listed it for $1,200 a month and had 20 people show up to see it. Rent on that property and others like it now runs $2,000 and higher, and Garrison estimates some of his Madisonville homes have appreciated 60% since purchase. Madison Road itself has been reshaped by developers replacing single-story retail, the kind that once housed an auto body shop and an ice cream parlor, with three and four story mixed-use buildings: retail on the ground floor, class A apartments above.
  • Madison Place, bordering Mariemont on the other side from Fairfax, sat at $80,000 to $120,000 for years while comparable Mariemont homes traded near $350,000, despite both being the same distance from downtown. That gap is now closing as buyers push into Madison Place and Madisonville looking for the value Fairfax no longer offers.
  • Newport, Kentucky has become Garrison's cross-river play as Ohio-side margins tighten. Property taxes there run lower than Hamilton County even though owners pay both city and county tax. The tradeoff is a stricter inspection process and a contractor pool that mostly is not licensed in Kentucky, which drove up Garrison's early rehab costs while he built out a new set of trade relationships.
  • Covington, just past Newport, is earning a look for the same reason: lower cost of ownership and, in Garrison's words, a neighborhood with good vibe worth familiarizing himself with.
  • Old Milford, where Garrison lives, is a small walkable pocket distinct from the broader Milford footprint. It carries turn-of-the-century two-story retail buildings with a single apartment over each storefront, recently anchored by Little Miami Brewing. The wider Milford area, by contrast, is mostly 1950s ranch stock inside 275 and 1990s-to-current subdivisions and class B multifamily further out.

The Mariemont School District Effect

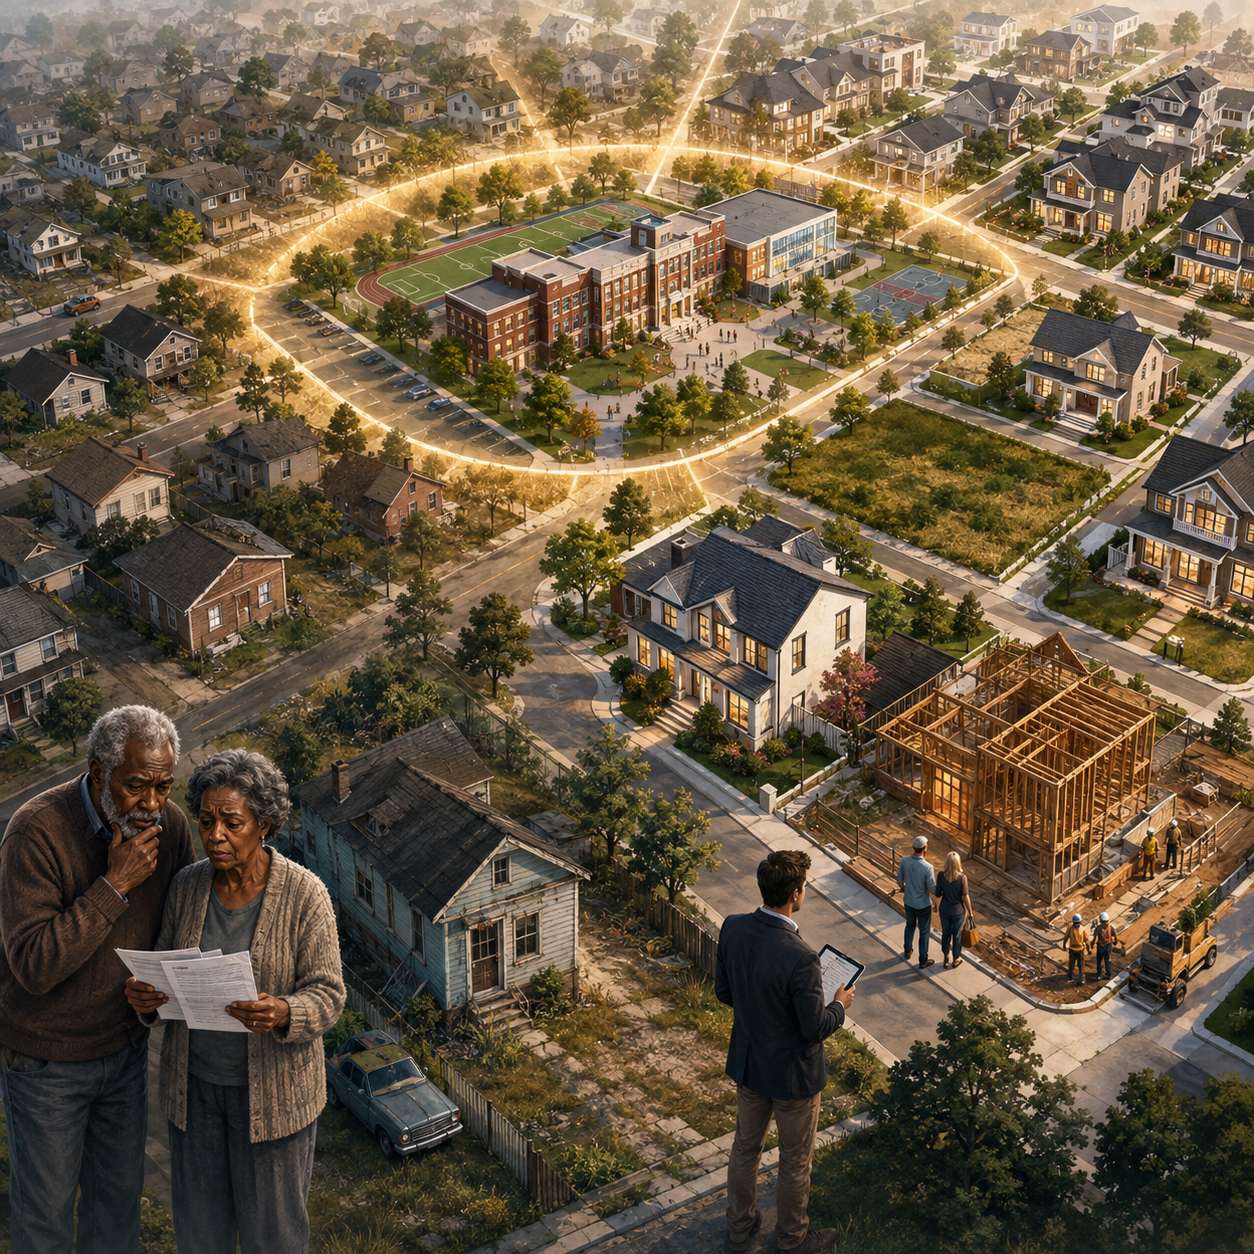
The clearest structural pattern in this conversation is a school district acting as a hard price line between adjacent neighborhoods. For years, a home in Mariemont carried a $350,000 price tag while an equally close, equally built Madison Place home sold for $80,000 to $120,000. Fairfax absorbed the same effect once buyers realized it shared the Mariemont district: land that once carried a stigma because of its Fairfax address is now marketed and priced as Mariemont schools.


That appreciation has a cost. Longtime Madisonville homeowners, some who have owned for 30 to 40 years, are now being squeezed by rising property tax valuations tied to the same appreciation investors are capturing. Garrison notes some are relocating to apartments because they can no longer carry the tax bill on a home they own outright. For an investor, this is worth tracking as both an opportunity signal and a reason to expect continued turnover in these corridors as the tax burden displaces longtime owners.


This is the throughline across Cincinnati real estate right now: proximity to a strong school district or a strong urban corridor is compressing what used to be wide price gaps between adjacent neighborhoods, and that compression is happening faster than it did a decade ago because information about these markets is far more available than it used to be.
What's Working in Cincinnati

Garrison's approach comes down to a small number of repeatable principles.

  1. Know your margin before anything else. Garrison defines this simply: what is left after your expenses and your mortgage are paid. Every acquisition decision runs through that number first.
  2. Concentrate in one area before you scale. Early on, especially before hiring a property manager, working scattered properties across neighborhoods wastes time and misses deal flow. Garrison picked up an off-market Fairfax flip simply because he was already renovating next door when the neighbor listed her house.
  3. Shift to value-add and fix-and-flip as a market tightens. In Madisonville, Garrison's read for 2026 is that the play is improving a property enough to force appreciation and resell it, rather than counting on a discount at purchase, since 6% interest rates and already-elevated prices have compressed that margin.
  4. Expand across the river when the home market compresses. Newport and Covington offer a real cost of ownership advantage, even accounting for double taxation and a more expensive first year of learning who to hire.

What is not working: buying in Madisonville expecting a discount. Garrison is blunt that the neighborhood is fully discovered now, and margins there keep getting tighter as more buyers compete for the same data everyone can see on Zillow and BiggerPockets.

Lessons From the Field: Surviving a Recession When Your Funding Partner Walks

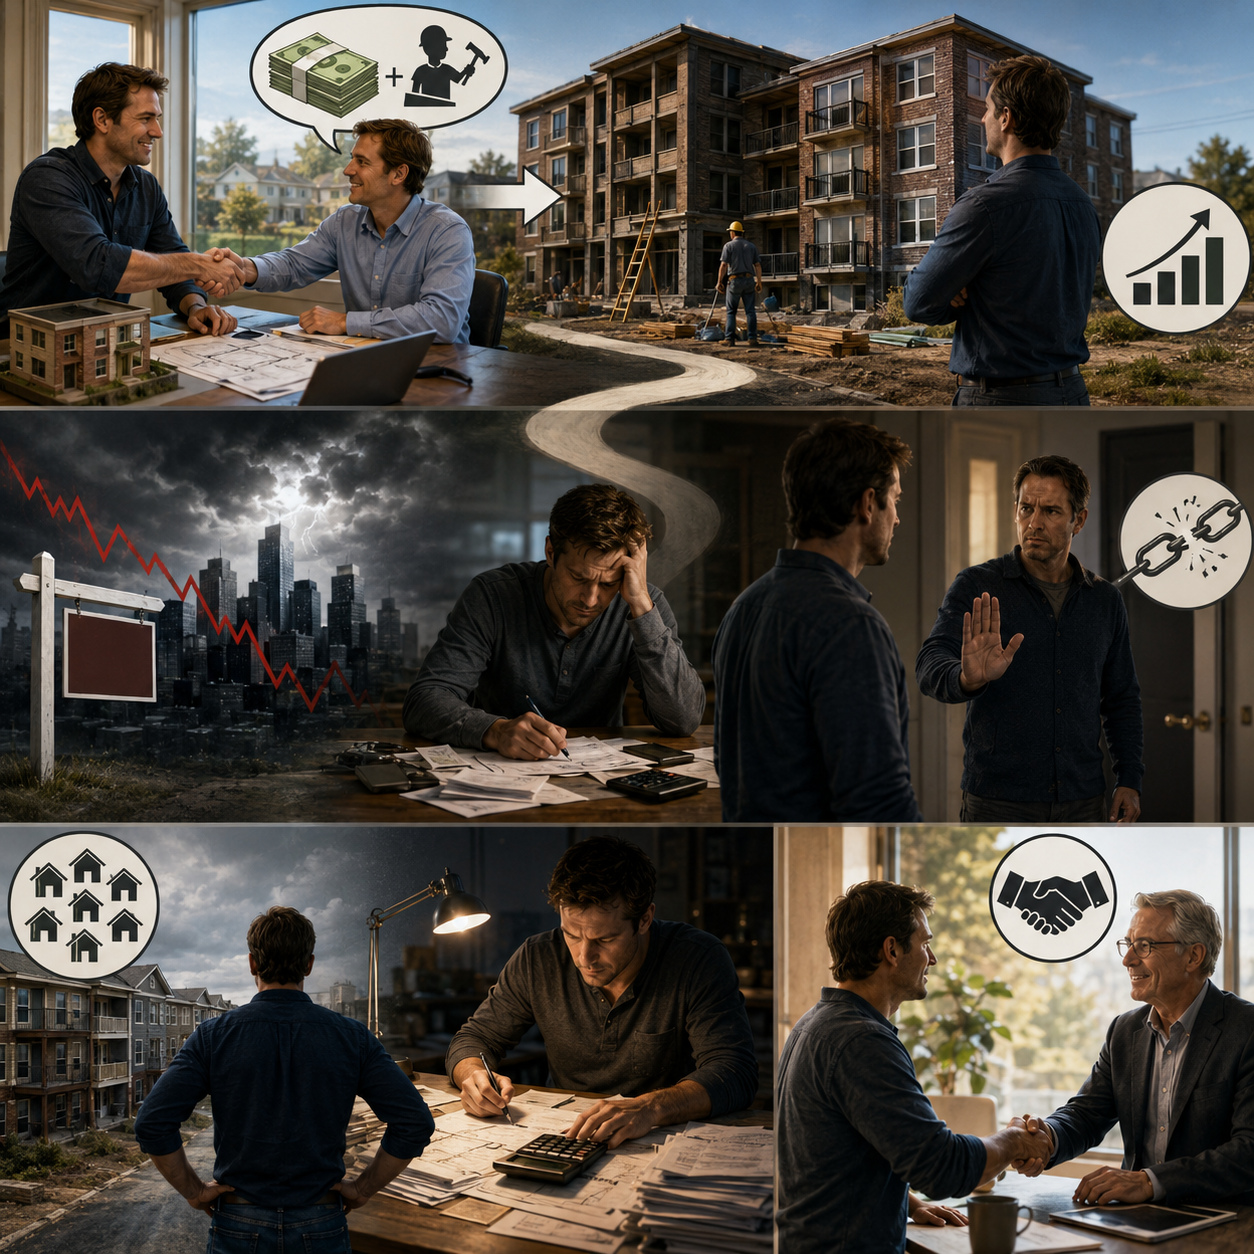
In 2005, Garrison was a newer real estate agent when a client offered a simple arrangement: the client would find capital and financing, and Garrison would locate properties and run the rehabs. The partnership worked well at first, and they scaled quickly into a portfolio of multifamily properties.


The problem was capitalization. They bought more than the partnership could comfortably carry, and the timing lined up badly. By 2008, the broader recession had arrived and the portfolio was already stretched thin. Garrison held on through several difficult years, but the real break came in 2012, when his business partner, going through a divorce, told him in person that he was done funding the properties.


Garrison had built his half of the arrangement on rehabs and hustle, not capital, and he was suddenly the one left holding roughly 100 units with no salaried partner behind them. He did not declare bankruptcy, but his credit score took a serious hit as he worked to sell down the portfolio during a recession. What got him through, by his own account, was a track record of keeping his word. A few lenders and counterparties gave him extra time when they did not have to, because of how he had dealt with them before.

The experience reset his risk tolerance completely. Garrison describes spending roughly five years afterward deliberately risk averse before he started slowly building his investment portfolio back, this time as a disciplined single-family buy-and-hold and flip investor rather than a leveraged multifamily operator.

  1. A partner's personal life is part of your deal risk. Garrison's funding disappeared because of a divorce, not a market event. Structure partnerships assuming the other side's circumstances can change without warning.
  2. Under-capitalization does not show up until conditions turn. The portfolio performed fine until 2008 exposed how thin the reserves actually were.
  3. A forced sale is still a skill worth having. Selling around 100 units during a recession, out of necessity, built the sales ability Garrison now relies on as a full-time agent.
  4. Reputation outlasts a credit score. Keeping commitments through the wind-down bought him grace from people who had no obligation to extend it.
  5. Risk tolerance needs a real reset period after a crisis. Five years passed before Garrison was ready to invest again, and he treated that timeline as necessary rather than something to rush.
October 14, 2026
How to Research the Cincinnati Market in Two Hours a Week
October 5, 2026
$110,000 from a wholesaler, $21,000 of work, a $200,000 appraisal. Ben Austin on the West Side streets he won't cross, and why he buys every property with two exits so he can decide later whether to flip or hold.
October 1, 2026
Cincinnati ranked fifth nationally for home price growth in April 2026, but the number that matters is replacement cost: whole neighborhoods still sell for less than it costs to build. Ian Cruz and Slocomb Reed answer the questions out-of-state investors ask first.
September 30, 2026
Venture has gone full cycle 32 times without missing pro forma. This year it offered rent concessions for the first time in 13 years. Robbie Hendricks on new supply, an 18-month soft stretch, and why every underwrite now assumes 0% rent growth.
September 29, 2026
How to Find Cash-Flowing Furnished Rentals in the Cincinnati Market in 2026
September 29, 2026
Contingent offers are back for the first time in five years and showings have slowed. Rebecca Sequeira, who has made money on every flip since 2016, on what she still buys, what she puts in every house, and when she cuts the price.
September 25, 2026
Self-manage if you're trying to save money. Hire out if you're trying to save time. Bri Leichliter built a Cincinnati property management company, sold it, and still owns five units — here's the math behind that split.
September 23, 2026
Houses that sold for $30,000 in Madisonville now trade at $125,000 to $150,000 still needing full renovations. A property manager with 700-plus units on where the next wave is going, and why the 12-unit building is the target.
September 22, 2026
Suburban office trades near a 10 cap while retail and industrial compress to six and seven. Tanh Truong on why half-empty office in Blue Ash is the one Cincinnati asset class where basis is still negotiable.
September 18, 2026
$1,900 in Winton Woods, $1,643 in Oak Hills, same bedroom count. What a 100-plus unit portfolio across nine districts reveals about which Cincinnati houses should stay rentals and which should be sold.
September 18, 2026
The renovation ran 2.5x over budget and produced 3x the rent bump. John Casmon on the Boone County data behind an 81-unit Florence buy, and the census-tract tool he uses instead of radius reports.
September 15, 2026
Cincinnati built almost no new apartments for 24 years. Gil Richards on the abatement math, which buildings qualify for historic credits, and why downtown is formally classified as Difficult to Develop.
September 11, 2026
Section 8 in Cincinnati: Why CMHA and Butler Metro Produce Different Returns
September 10, 2026
A rate cap that cost $30,000 renewed at $1.3 million. Joe Fairless on the first two losing sales in Ashcroft Capital's history and why Greater Cincinnati never had the spread to lose.
September 9, 2026
A $180,000 all-in flip selling for just under $270,000, with no cash out of pocket. Slocomb Reed breaks down four Greater Cincinnati deals, and why none of them depended on the market going up.
September 5, 2026
West Newport houses sold for $10,000 in 2016 and now go for $80,000 needing full rehabs. Garth Kukla on why proximity to a walkable corridor predicts Northern Kentucky value better than which city a property sits in.
September 4, 2026
The Hamilton County timeline from a missed rent payment to a set-out; and why TLP's Izzy Ong treats every case that reaches a magistrate as a failure of the process, not a win.
September 3, 2026
A $450,000 Loveland listing sold for $570,000 cash. Ethan Bishop on which Greater Cincinnati submarkets are drawing multiple offers, which have quietly cooled, and the two-generation demand pattern driving both.
September 2, 2026
Off-street parking, galvanized plumbing, school district lines that don't follow township borders, and a tax bill that can quadruple at closing. The Cincinnati-specific due diligence most investors skip.
August 31, 2026
JD Schmerge brokers Greater Cincinnati multifamily and operates a 7-unit in South Covington. Why tenants aren't paying for upgraded finishes, why insurance and taxes now outweigh interest rates, and how much to renovate before selling.
August 28, 2026
Bret Halsey went from pro soccer to 70-plus units in under three years, 14 of them fourplexes. How Cincinnati's repeating 1960s floor plans make the city's most common multifamily building the easiest one to underwrite.
August 27, 2026
Nine of 24 units were paying rent. Slocomb Reed took over management three months before closing, cleared the building, and proved higher rents; all before owning a share of it.
August 27, 2026
Reading, Ohio: Cincinnati's Unlikely Development Hotspot
August 26, 2026
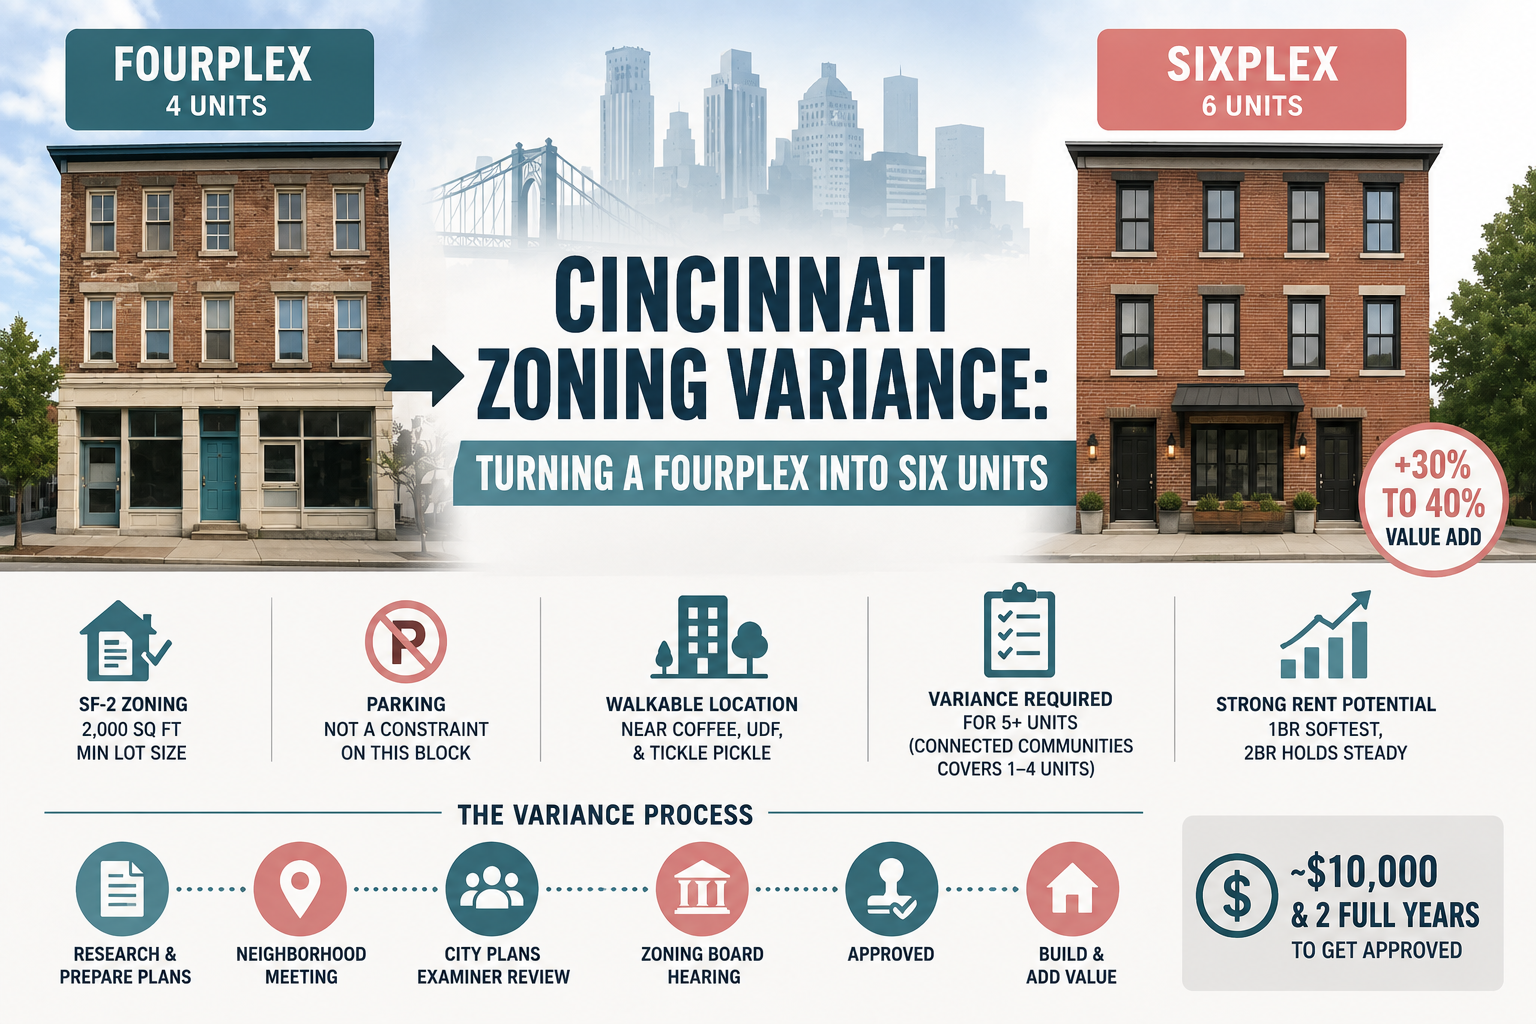
Two years, roughly $10,000 in zoning costs, and about 40 neighbor signatures. What Jeremy Komer's Northside conversion reveals about Cincinnati's variance process and the gap in Connected Communities.
August 25, 2026
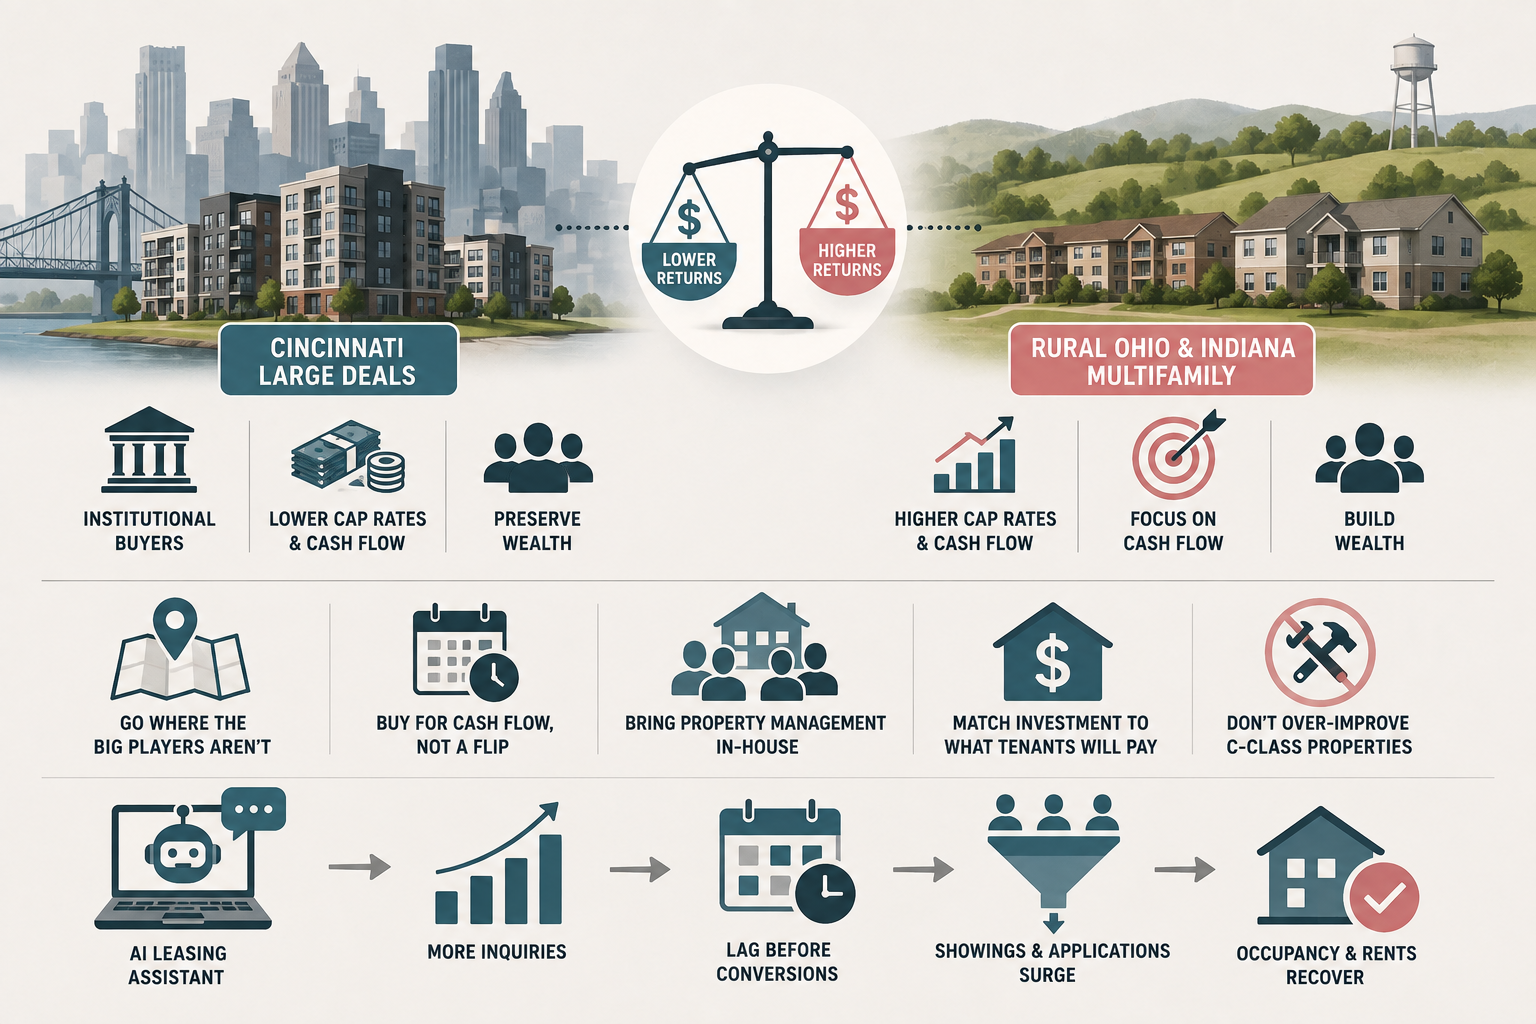
Lee Yoder holds 930 units, and almost none of them are near Cincinnati. Why institutional capital compresses returns above 100 units, and what he found in rural Ohio and Indiana instead.
By Ian Cruz • August 20, 2026
How Ian Cruz and Slocomb Reed used four defined roles to scale from an 8-unit Northside deal to 73 units in under two years — plus what Cincinnati's rental data shows right now.
August 20, 2026
Hedge funds are gone, rates broke the buy-and-hold math, and Cincinnati's off-market deal flow now turns block by block. Where the deals are and what buyers inherit when they sign.
August 20, 2026
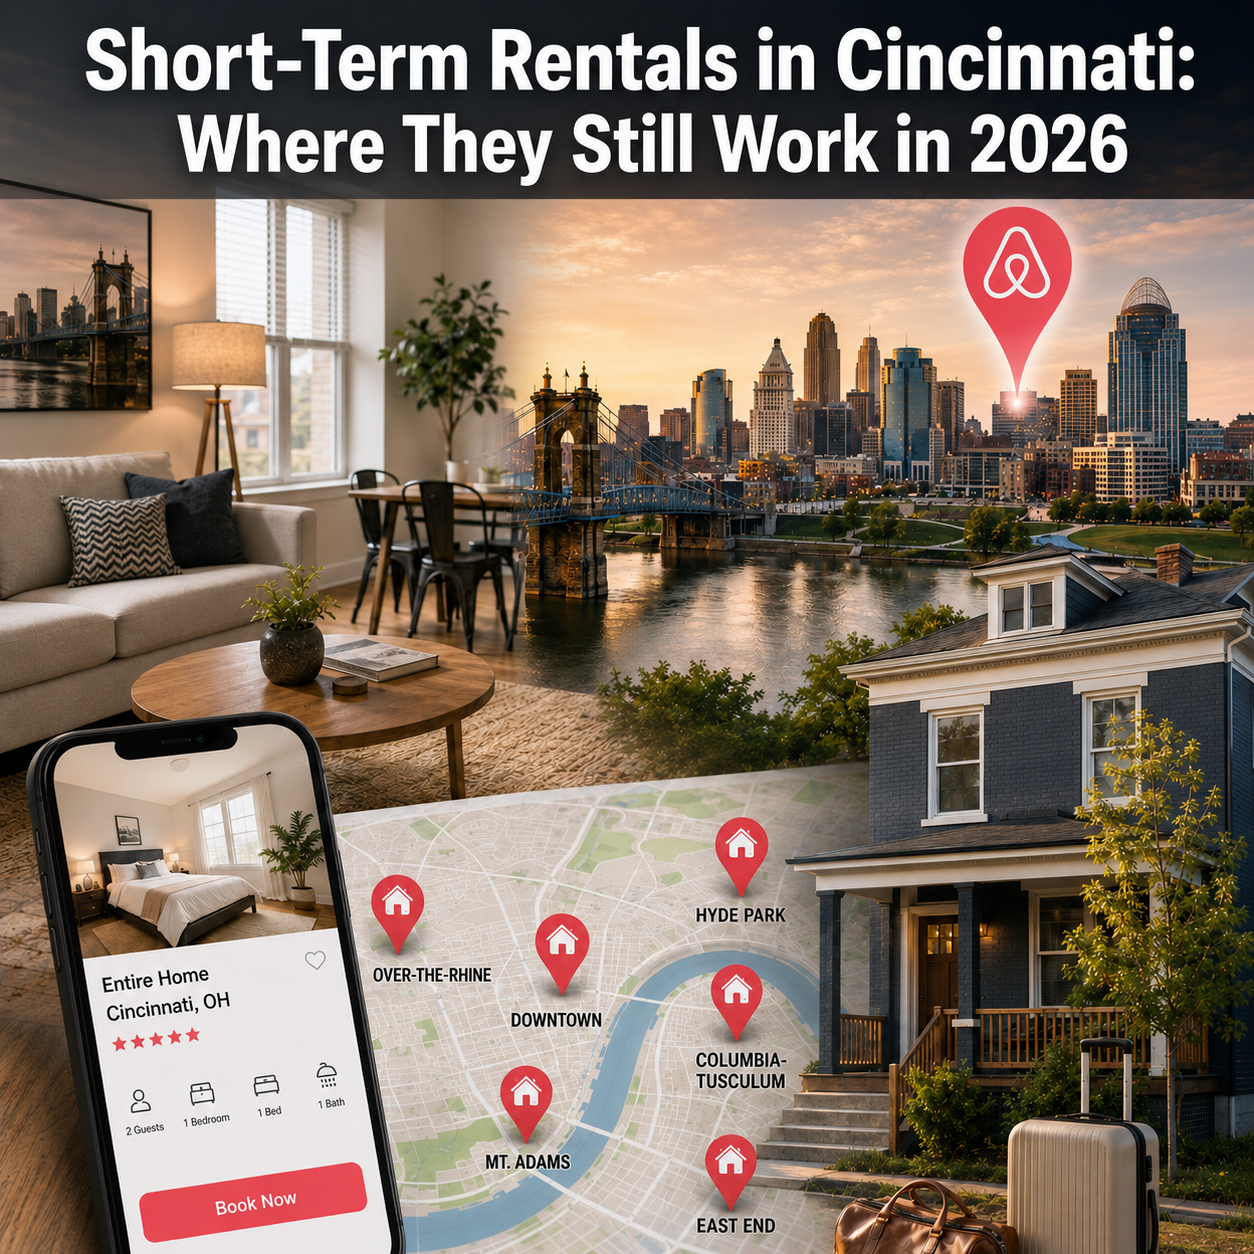
A neighborhood-by-neighborhood map of where short-term rentals are legal in Greater Cincinnati; and what the flattening market means for the ones that are.
August 18, 2026
What 300+ Transactions Reveal About Cincinnati’s Best Investment Strategies
June 12, 2026
Madisonville, Fairfax, and Newport: Where Cincinnati Investors Are Finding Margin in 2026
By Ian Cruz • June 5, 2026
Flip vs. BRRR: Which Cincinnati Neighborhoods Favor Which Strategy