Cincinnati Multifamily in 2026: Underwriting for 0% Rent Growth
Venture has gone full cycle 32 times without missing pro forma. This year it offered rent concessions for the first time in 13 years. Robbie Hendricks on new supply, an 18-month soft stretch, and why every underwrite now assumes 0% rent growth.
Since 2013, Venture Real Estate Company has acquired more than 3,600 multifamily units across Greater Cincinnati. It operates about 2,000 of them today and has gone full cycle 32 times, hitting or beating pro forma on every exit. This past year it offered rent concessions for the first time in 13 years. Partner Robbie Hendricks says every underwrite the firm runs now assumes 0% market rent growth.
About This Post
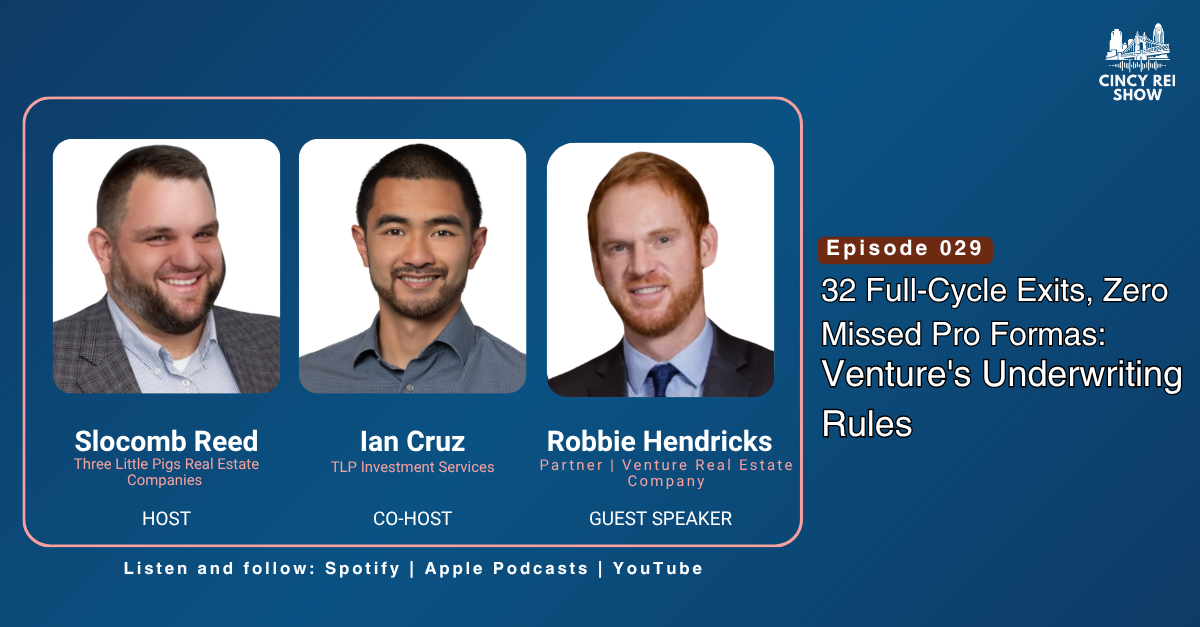
This analysis draws from a conversation with Robbie Hendricks, a partner at Venture Real Estate Company. He grew up in Finneytown, Evendale and Montgomery and went to Xavier. Venture self-manages its portfolio, which runs from Westwood 11-units to suburban communities in Loveland and Eastgate. That gives Hendricks a direct read on leasing, supply and pricing across the cycle.
Listen to the full conversation on Spotify, Apple Podcasts, and YouTube. The full episode also covers how Venture decides when to sell and Hendricks' take on Hamilton and the Spooky Nook effect.
The Cincy REI Show publishes every Monday. New episodes cover neighborhood-level analysis, local investor strategies, and real deal stories from operators active in Greater Cincinnati.
Where New Supply Is Pressuring Greater Cincinnati Apartments
In Cincinnati, new apartment construction never fell off a cliff the way it did in the Sun Belt. Hendricks expects it to keep parts of the region soft for the next 18 months.
- Eastgate and Loveland are where Venture feels it most. Its renovated 1980s and 1990s properties there now compete with new deliveries that come with concessions and more modern amenities.
- West Chester and Liberty Township are seeing the same pattern. Investors expected new supply to dry up there, and it has kept coming.
- Hebron, Kentucky is getting Hebron Station, a new build by BRG. Legacy Cincinnati owners like BRG, Fath and Hills hold 5,000 to 10,000 units each and have enough capital to build even when a development pencils poorly for newer firms. PLK is also building heavily across the region.
- Montgomery Quarter and PLK's newest product set the amenity bar. Hendricks says a B+ property renting within about $500 a month of those communities will struggle to lease. It has to upgrade its amenities or lower its rent.
- Landen and Maineville hold Nantucket, which Fath built in 2004 as A+ product. It is a live test case for when an aging Class A property slips into B.
- Hamilton has momentum. There is public investment in downtown, new restaurants like Agave & Rye, and demand spilling over from Liberty and West Chester. 80 Acres, which had roughly 200 to 300 employees, recently went under, and a lot of new apartments are going up there too.
- Westwood and Cheviot are where Venture started. The properties were affordable, there were few renovated units, and absentee owners gave poor service. Local broker Steve Turman helped the partners find their early 11-unit, 28-unit and 34-unit deals there.
A standout example of a C-class asset in an A-class market: Venture bought a 1970 property less than a mile from downtown Loveland. It was known as the one place in town to avoid. Venture turned it around and added a clubhouse and pool to compete with CMC's new construction nearby.
Why Cincinnati Real Estate Cap Rates Held While the Sun Belt Reset
Transaction volume in larger Cincinnati multifamily is way down. Rates are volatile, and many would-be sellers are still anchored to 2022 valuations that no longer pencil.
What Cincinnati lacks is distress. The reasons:
- Cap rates never compressed as far here. In submarkets of Dallas, buyers paid 3 caps for 1970s and 1980s B-class product. Those deals now trade in the 6s or higher, and many blew up. Cincinnati never saw that level of euphoria.
- Less floating-rate debt. Bridge loans and variable-rate debt existed in Cincinnati, but far less of it than in the Sun Belt.
- Cash flow can still cover the debt. Host Slocomb Reed notes that local cap rates have stayed roughly in line with post-2023 interest rates. When a loan balloons, Cincinnati owners can usually hit the DSCR to refinance. One Venture deal bought at the wrong point in the cycle still refinanced into seven-year agency debt and keeps cash flowing for its investors.
Hendricks estimates Cincinnati rents grew about 25% between 2020 and 2024. In his view, that pulled years of future rent growth into the present, and the market is still absorbing it.
The long-term story is affordability and jobs. Venture's latest investor update highlighted several signals:
- Fortune reported that Florida and Texas are the biggest losers in the housing market and Ohio is the surprise winner.
- Cincinnati ranks fifth among Midwest cities for homeownership under age 35, at 17%.
- Biomanufacturing firm Resilience moved its headquarters from San Diego to southwest Ohio.
- Billionaire Ratmir Timashev wants to turn Ohio into an AI hub, according to Forbes.
- Anduril won a major Air Force fighter program, putting Ohio at the center of military tech.
For Hendricks, a balanced housing market where people can still afford to buy makes Cincinnati easier to underwrite than the boom-and-bust metros.
What's Working in Cincinnati
Venture's 2026 underwriting rules:
- Lead with cash flow. Every deal has to reach a 10% cash-on-cash return by a year-three to year-five stabilization.
- Assume 0% market rent growth. That holds even on value-add, where a 1970s property is being brought back to life.
- Model concessions in years one and two wherever new supply is delivering nearby.
- Underwrite over 7 to 10 years. Deals have to work on a long hold.
- Protect your basis against new construction. Overpay for 2004 product, then renovate it, and you are all-in at the same price as a brand-new building that undercuts your rent. A 1994 B-class property bought at the right basis can rent at a discount to new supply and still work.
Hendricks says new supply has changed Venture's underwriting. The buy box shifted for a different reason: the firm's growth. As Venture hires and scales, it is moving away from scattered-site management and C-class submarkets toward 1980s-and-newer product in B-class submarkets, where processes are easier to systematize.
How to grade a property. Hendricks rates the asset and the market separately.
- An A-class market has good schools, high median household incomes, low crime and people out jogging.
- C-class assets include nearly everything built in the 1970s or earlier. Reed pictures Cincinnati's brick-bunker four-family and 12-family buildings, two and a half stories tall, built from the 1940s through the late 1970s.
- B-class is where it gets gray. Some 1980s brick buildings are close to maintenance-free and grade as B or better. A neglected 1992 property that needs heavy CapEx can grade as C. The 1975 to 1995 range is judged deal by deal, based on how much work it needs. Reed adds forced-air HVAC as a B-class marker, since C stock tends to run on boilers, baseboard electric and through-wall units.
- Class A is defined by amenities: dog-wash stations, pickleball courts, gyms and lobby workspace. Venture added a pickleball court at a 2000-built property, and residents love it.
Scaling into larger deals. Hendricks has three pieces of advice for operators moving from four units to 40 and beyond:
- Build LP relationships before you need the money. Raising in a hurry comes across as desperate.
- Show mastery at each size before moving up. Venture's 11-unit and 34-unit deals built the track record that got it considered for a 68-unit.
- Target portfolios of smaller properties over single 150- to 200-unit assets. Big deals sold by brokers like Kurt Shoemaker, Matt Newcomer and Nathan Murphy trade efficiently against institutions with lower cost of capital. Small-property portfolios are messier, and that is where newer buyers find discounts. Reed and co-host Ian Cruz recently bought one from a distressed seller at a discount that does not exist at 120-plus units.
What doesn't work: reading every buyer who pays more as overpaying. Some groups run on longer horizons or cheaper capital. Venture only bids to its own LP return requirements.
Lessons From the Field: The First Concessions in 13 Years
For 13 years, Venture never gave away a free month. Rents rose at every renewal, and occupancy sat near 98%.
Then new deliveries on the east side and in the northern suburbs started leasing with concessions. Some of Venture's nicer properties dropped to 88% and 89% occupancy.
The team had never offered concessions and had to work out the basics, like whether to offer them only on new leases or on renewals too. Every leasing process got stress-tested. Hendricks says a strong market had hidden operational inefficiencies for years across the industry.
Venture responded by competing on amenities and on rent gaps as small as $50. It also started offering 18-month and 24-month leases so that expirations don't bunch up during the next 18 months of expected softness.
Today Venture offers no concessions, and its stabilized portfolio is at 95% occupancy. Hendricks counts that as a sign the new supply is being absorbed.
- A strong market can hide weak operations. Years of 98% occupancy made operators look better than they were.
- Settle your concession policy before you need it. Decide ahead of time who gets them, new leases or renewals, and for how long.
- Use lease length as a tool. Staggered 18- and 24-month terms protect the rent roll through a soft stretch.
- Small rent gaps matter in a competitive market. $50 a month can decide a lease when new product is offering a free month.
- Treat a soft market as a stress test. Venture came out with tighter systems and back at 95%.